Refining Industry Automation Software Market: Size, Trends, and Key Players (2025-2035)
Key takeaway: The refining industry automation software market — the DCS, SCADA, MES, and safety systems that run refineries — is valued at about $5.9 billion in 2025 by WiseGuyReports, growing to $10.5 billion by 2035 at roughly 5.9% annual growth; broader-scope estimates (MarketResearchFuture) put it near $20.3 billion in 2025. Efficiency pressure, tightening safety rules, and AI-driven predictive maintenance are the main growth engines.
What the refining industry automation software market covers
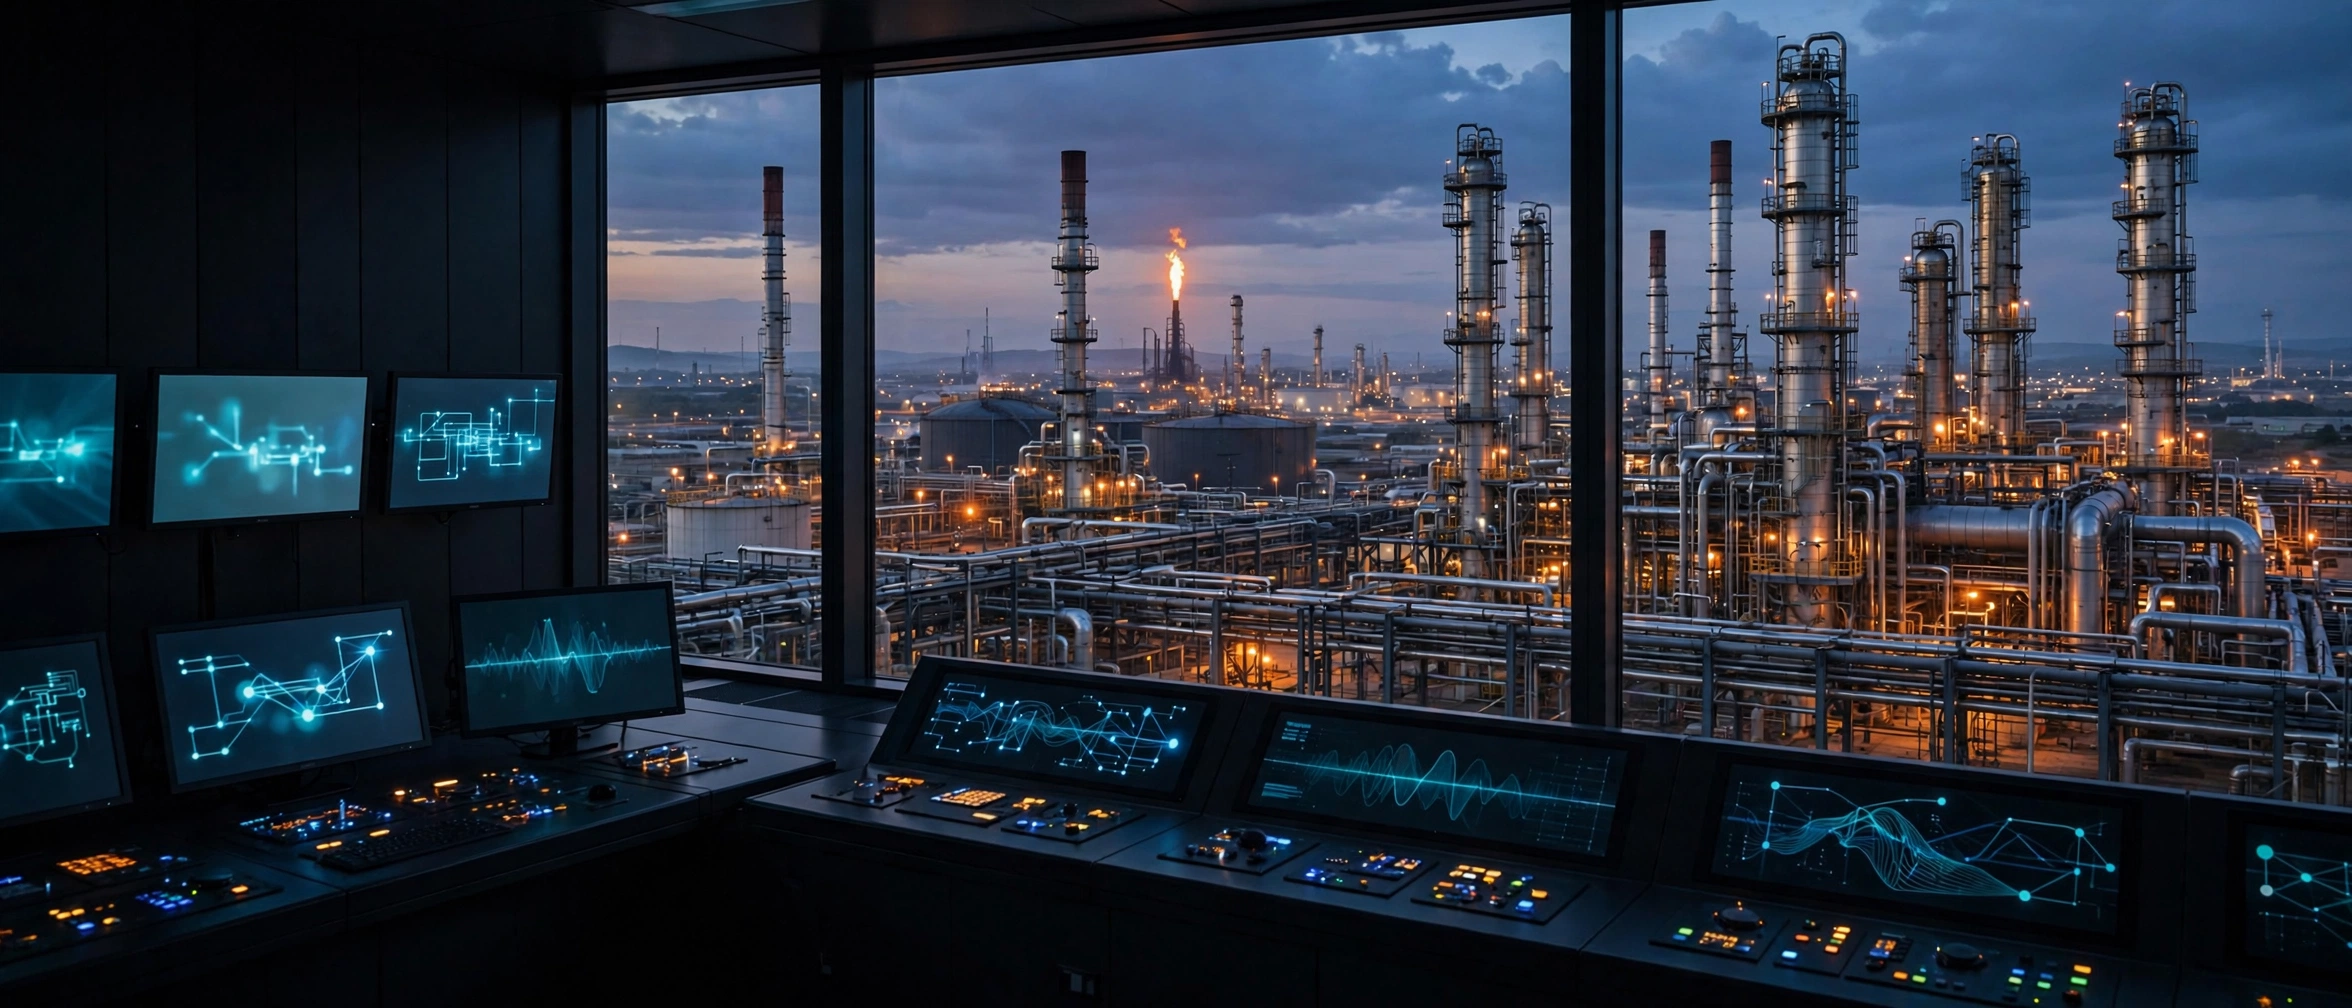
When analysts talk about the refining industry automation software market, they mean the software layers that monitor and control what happens inside a refinery. This is not the hardware alone — the valves, sensors, and pumps — but the software that ties them together:
- Distributed Control Systems (DCS) — the central platform coordinating refining units in real time.
- SCADA systems — supervisory monitoring and data acquisition across the plant.
- Manufacturing Execution Systems (MES) — production scheduling and execution.
- Safety Instrumented Systems (SIS) and process safety management software.
- Advanced process control (APC) and predictive maintenance analytics.
- Supply chain management, asset management, production planning, and laboratory automation software.
Deployment comes in three flavors: on-premise, cloud-based, and hybrid. End users span refineries, petrochemical plants, and chemical processing facilities. Understanding this scope matters, because it explains why market estimates differ so much — narrow definitions track pure refining automation software, while broad ones roll in adjacent oil-and-gas automation spend.
How big is the refining automation software market in 2025?
Two recently published reports put the numbers in context, and they disagree in a useful way:
- WiseGuyReports sizes the dedicated refining automation software market at $5.59 billion in 2024 and $5.92 billion in 2025, forecasting growth to $10.5 billion by 2035 at a compound annual growth rate (CAGR) of about 5.9%.
- MarketResearchFuture uses a broader scope (including upstream and adjacent process-industry automation) and reports $19.52 billion in 2024, rising to $20.27 billion in 2025, with a forecast of $29.43 billion by 2035 at roughly 3.8% CAGR.
- For additional context, The Business Research Company’s industrial automation in oil and gas report puts the wider oil-and-gas automation market at $18.75 billion in 2025, growing to $27.98 billion in 2030 at about 8.4% CAGR — driven by digital oilfield adoption, remote operations, and AI analytics.
The honest read: the refining-specific software slice is likely in the mid-single-digit billions today, with the broader automation-and-software ecosystem roughly four times larger. Growth is steady rather than explosive — refineries buy automation in 3- to 5-year modernization cycles, not overnight.
What is driving growth in refining automation software?
According to the report publishers and industry analyses, five forces are doing most of the work:
1. Operational efficiency and cost reduction
Refineries run on thin margins. Automation software for real-time monitoring, advanced process control, and production optimization directly cuts operating costs and boosts throughput — the single biggest driver cited across reports.
2. Safety regulations and compliance
Tightening environmental and process-safety rules are pushing refineries toward software that delivers accurate data collection, real-time emissions reporting, and automated controls. Process Safety Management and Safety Instrumented Systems are no longer optional extras.
3. Predictive maintenance and AI analytics
Predictive maintenance software is one of the fastest-growing segments. One market analysis notes that nearly half of refineries now deploy predictive analytics, achieving up to 30% savings on maintenance-related expenses. AI and machine learning models forecast equipment failures before they happen, cutting unplanned shutdowns — the most expensive event in a refinery’s calendar. (For context on how manufacturers use AI for energy and process optimization, see our coverage of AI energy optimization in manufacturing and AI in batch process optimization.)
4. Cloud and remote operations
There is a clear shift toward cloud-based refinery automation solutions, which offer flexibility and scalability that on-premise systems cannot match. The pandemic-era push toward remote monitoring accelerated this trend, and vendors now compete on hybrid deployment options.
5. Cybersecurity for operational technology
As refineries connect more systems to the cloud, OT cybersecurity has become a board-level concern. Vendors that build security monitoring, timely patching, and compliance features into their platforms — such as Honeywell’s Experion and ABB’s integrated offerings — hold a competitive edge.
Key vendors in the refining automation software market
The market is consolidated: the top five to six vendors hold the majority share, reflecting decades of accumulated expertise and high switching costs (estimated at $2.4–$6.8 million per facility for a DCS migration). The names that appear across every major report:
- Honeywell (Experion PKS, UniSim) — strong in refining, chemicals, and cybersecurity-hardened automation.
- Emerson (DeltaV, Ovation) — process automation with emphasis on reliability and predictive maintenance.
- Siemens (SIMATIC PCS 7) — integrated automation with strong cybersecurity certification (IEC 62443).
- ABB (System 800xA, ABB Ability) — process and hybrid automation with electrical integration.
- Yokogawa (CENTUM VP, FAST/TOOLS) — high-fidelity process control, particularly strong in Asia.
- Schneider Electric (EcoStruxure, AVEVA) — SCADA and energy management via the AVEVA portfolio.
- Rockwell Automation (FactoryTalk, PlantPAx) — tight hardware-software integration.
- Aspen Technology — advanced process control and asset optimization software.
- KROHNE and Endress+Hauser — instrumentation and measurement software.
Services — consulting, implementation, training, and lifecycle support — remain a major revenue stream, since refineries need help designing strategies, integrating legacy systems, and upskilling their workforce.
Analysis: what the numbers really signal
The following is analysis based on the verified data above, not a new fact claim. The market’s consolidation means this is an incumbent’s game: platform lock-in, training investment, and integration depth make it very hard for newcomers to dislodge Honeywell, Emerson, Siemens, ABB, or Yokogawa. The real battleground is software — AI analytics, digital twins, and cloud delivery — not hardware. For professionals, the implication is that OT cybersecurity and data analytics skills will outpace pure controls-engineering demand over the next decade. For investors, the steady mid-single-digit CAGR means this is a cash-flow story, not a hyper-growth story, with the fastest expansion in APAC refinery builds and brownfield modernization in the Middle East and India.
Who should care about this market?
- Automation and controls engineers — understanding vendor consolidation helps in career planning and certification choices.
- Refinery operators and IT/OT leaders — modernization cycles are expensive; knowing the software landscape prevents lock-in mistakes.
- Investors and analysts — the market’s stability and replacement-cycle economics make it a predictable, if unglamorous, segment.
- Students — predictive maintenance, digital twins, and OT cybersecurity are the growth skills attached to this market.
Frequently asked questions
What is the refining industry automation software market?
It is the market for software that monitors and controls refinery operations — including distributed control systems (DCS), SCADA, manufacturing execution systems (MES), safety instrumented systems, advanced process control, and predictive maintenance analytics. Estimates of its size depend on how broadly analysts define the software boundary.
How big is the refining automation software market in 2025?
WiseGuyReports estimates it at $5.92 billion in 2025, growing to $10.5 billion by 2035 at about 5.9% CAGR. MarketResearchFuture, using a broader scope that includes adjacent process-industry automation, estimates $20.27 billion in 2025, rising to $29.43 billion by 2035 at roughly 3.8% CAGR.
Who are the main vendors in refinery automation software?
The leading vendors are Honeywell, Emerson, Siemens, ABB, Yokogawa, Schneider Electric (AVEVA), Rockwell Automation, Aspen Technology, KROHNE, and Endress+Hauser. The top five to six suppliers collectively hold well over half of the DCS market in oil and gas.
What are the main growth drivers?
Operational efficiency and cost reduction, tightening safety and environmental regulations, AI-driven predictive maintenance, the shift to cloud-based and remote operations, and growing cybersecurity requirements for operational technology are the primary drivers.
Is cloud adoption growing in refinery automation?
Yes. Reports highlight a clear shift toward cloud-based and hybrid refinery automation solutions for flexibility and scalability, accelerated by remote monitoring needs. Vendors are increasingly competing on cloud delivery, digital twins, and API-first, data-driven platforms.
Sources
- WiseGuyReports — Refining Automation Software Market Analysis & Forecast 2035
- MarketResearchFuture — Refining Automation and Software Market Size 2035
- The Business Research Company — Industrial Automation Oil and Gas Global Market Report 2026 (via GII Research)
- Dataintelo — Oil Distributed Control Systems (DCS) Market 2025–2034