Service Delivery Automation Market Explained: Size, Segments, and How to Choose
Key takeaway: The service delivery automation market covers the software and services that automate how organisations deliver IT and business services — from ticket routing and incident response to onboarding and billing. Analysts disagree sharply on its size because they define it differently, but all agree on the direction: fast growth driven by AI, cloud delivery, and pressure to cut service costs.
If you have ever raised an IT ticket and watched it get routed, approved, and fixed without speaking to a person, you have seen service delivery automation in action. It turns service work — requests, incidents, changes, approvals — into repeatable workflows instead of manual hand-offs.
What is service delivery automation?
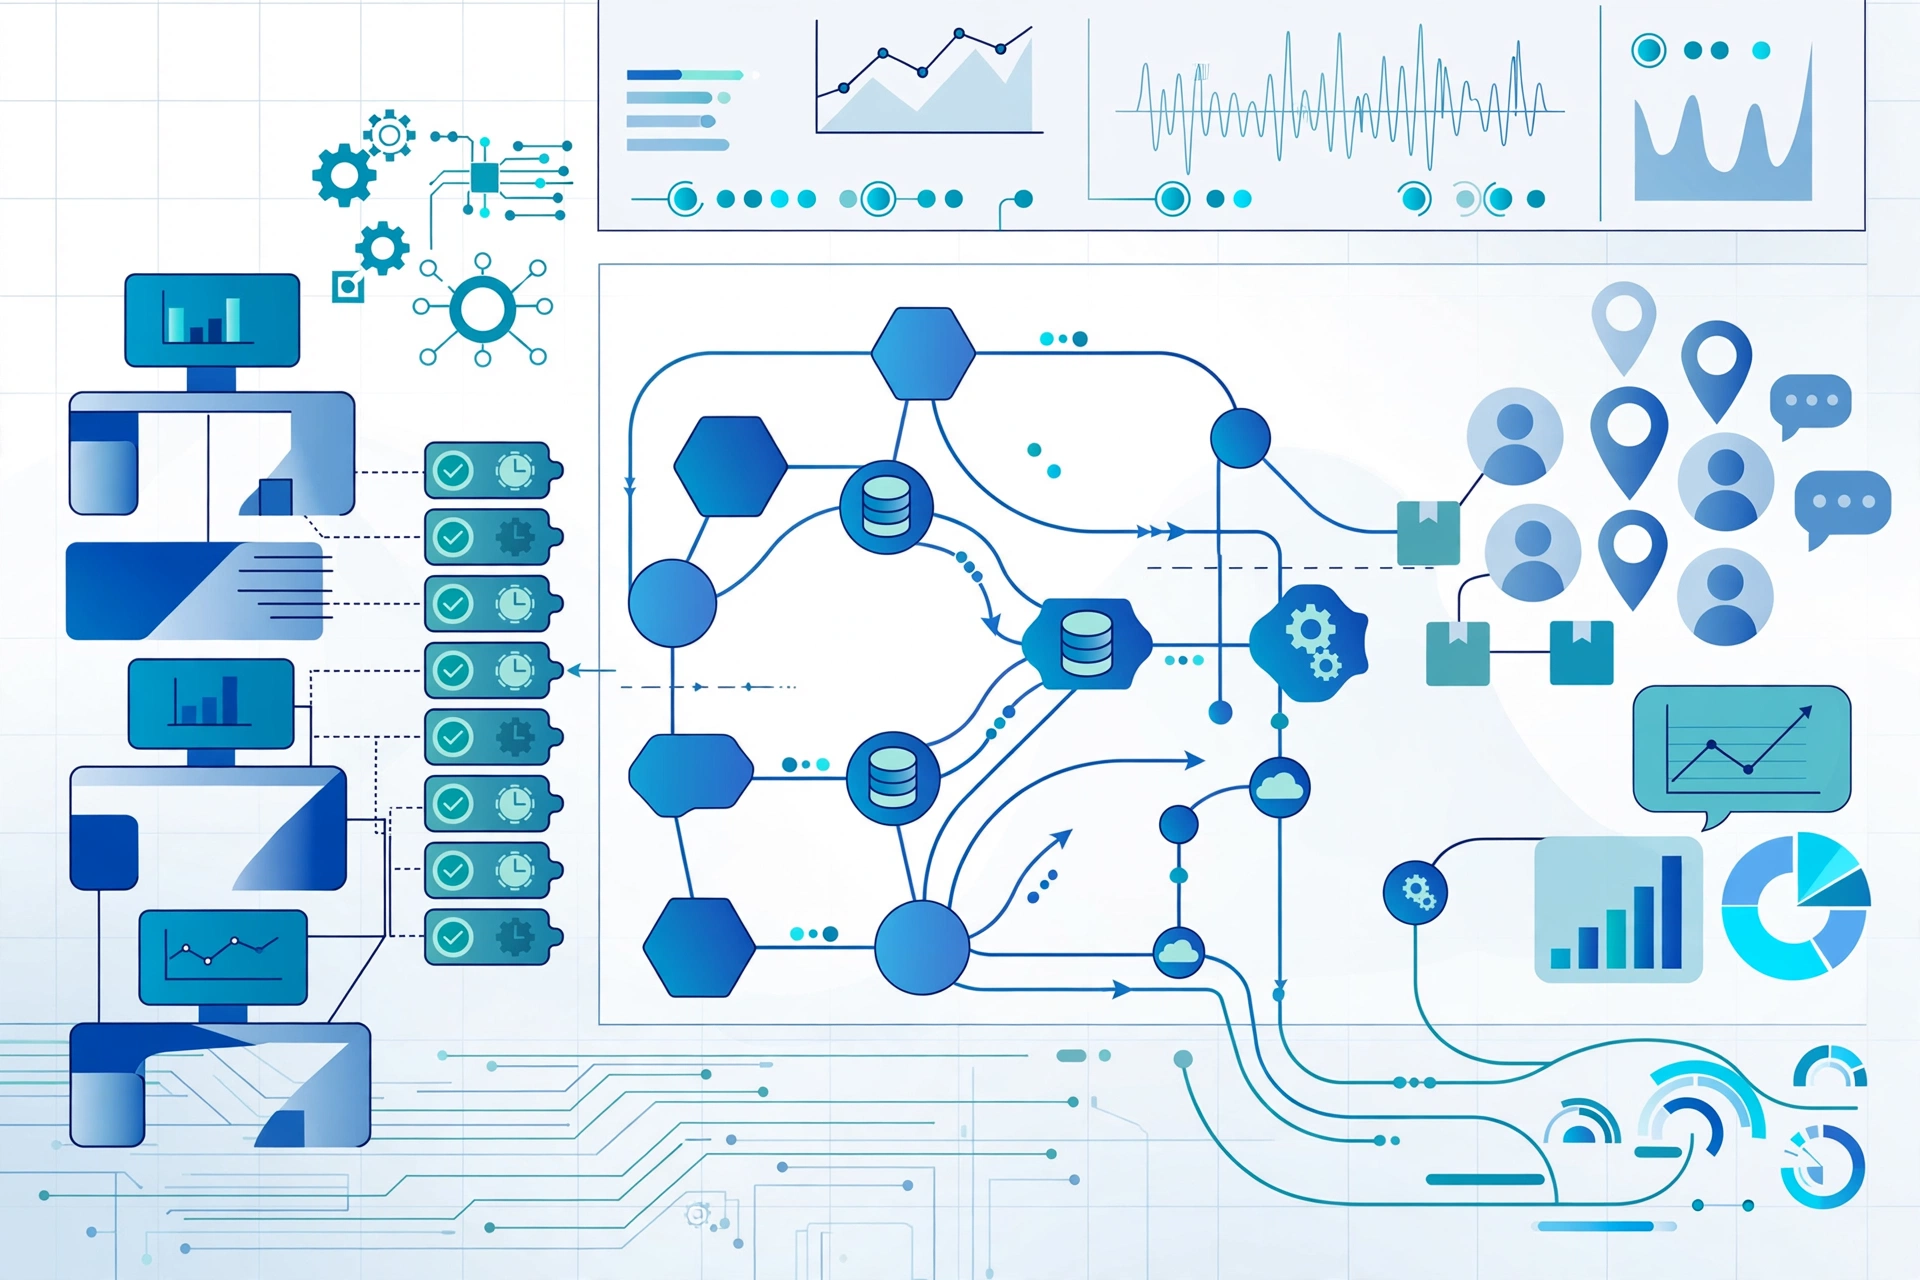
Service delivery automation is the use of software to carry out service processes with little or no human intervention. In IT service management (ITSM), workflow engines handle routine tasks such as ticket assignment, approvals, and follow-up notifications, as Alloy Software explains. A familiar example is automated incident resolution: when a root problem is marked resolved, the system closes related tickets, creates a knowledge-base article, and notifies everyone affected.
The scope goes wider than IT, covering customer onboarding, order fulfilment, claims handling, and employee service requests. That breadth is why market estimates vary so much: one analyst counts only IT service automation, another counts the whole business-process automation stack around it.
How big is the service delivery automation market?
The honest answer is that it depends on who is counting. Two independent research firms put the 2025 market at very different levels, and the gap itself is the most useful fact for a buyer: never compare vendors or budgets on a single market-size number without checking what it includes.
| Source | 2025 estimate | Forecast | Implied growth |
|---|---|---|---|
| Mordor Intelligence | USD 39 billion | USD 159.27 billion by 2031 | 26.43% CAGR, 2026–2031 |
| Dataintelo | USD 11.4 billion | USD 32.83 billion by 2034 | 12.4% CAGR |
Mordor Intelligence expects growth from USD 39 billion in 2025 to USD 49.31 billion in 2026 and USD 159.27 billion by 2031, driven by lower operating costs, faster cycle times, and hyperautomation — the combination of robotic process automation (RPA), AI, and low-code tools. Dataintelo, using a narrower definition, sizes the market at USD 11.4 billion in 2025 and USD 32.83 billion by 2034.
Within Mordor Intelligence’s broader view, IT process automation led with 55.40% of the market in 2025, software platforms held 61.05% of revenue, cloud deployment accounted for 60.75%, and banking, financial services, and insurance (BFSI) was the largest end-user industry at 22.20%.
What is driving growth in the service delivery automation market?
Service volumes keep rising while service teams do not: every new app, device, and digital channel creates tickets, requests, and changes. AI has also moved automation beyond rigid rules — natural-language triage, suggested knowledge articles, and predictive alerts now handle messier work. And cloud delivery has lowered entry costs, which is why Mordor Intelligence expects small and medium-sized businesses to be the fastest-growing buyer group, at a 31.20% CAGR to 2031.
Service delivery automation vs RPA vs ITSM
These terms overlap, and vendors blur them deliberately. ITSM is the discipline and toolset for delivering IT services — the service desk, service catalogue, knowledge management, and configuration database described by TechTarget. RPA is one technique: software robots that mimic human clicks in existing applications. Service delivery automation is the broader outcome: the end-to-end automated service, which may use RPA, workflow engines, AI, and integrations together.
| Approach | Best for | Limit |
|---|---|---|
| ITSM platform | Running the service desk and catalogue | Automation depth depends on the workflow engine |
| RPA alone | Repetitive clicks in legacy apps | Brittle when screens or processes change |
| Service delivery automation | End-to-end services across teams | Needs clean processes and governance to scale |
Analysis: if a vendor’s “automation” only automates one team’s clicks, you have bought RPA, not service delivery automation. The test is whether a request can travel across departments, with approvals and SLAs, without manual re-keying.
What does service delivery automation cost?
There is no standard price: most platforms charge by users, agents, workflows, or consumption, and vendors rarely publish comparable rates. Budget in three layers: the platform subscription, implementation and integration (often the largest first-year cost), and ongoing ownership — process design, monitoring, and change management. See our guide to low cost intelligent automation for a sense of scale.
How to choose a platform: prerequisites first
Start with prerequisites, not a vendor shortlist. You need a service catalogue, named process owners, and clean data on request volumes and resolution times — without those, automation encodes confusion. Then shortlist on four tests: integration with the systems your service already touches, workflows non-developers can build and change, honest SLA reporting, and approvals plus audit trails for regulated work. Pilot one high-volume, low-risk service — password resets or access requests — and measure first-response time, resolution time, and agent hours before and after. Related reading: dynamic AI agents and our trust layer for AI explainer.
Risks and limits to watch
A workflow built on a broken process locks the breakage in. Over-automation frustrates customers when there is no human escape route, and AI triage can misroute sensitive requests — in healthcare or finance, that is a compliance problem, not just an annoyance. Keep a human in the loop for high-stakes decisions, publish an escalation path on every automated service, and review outcomes monthly. What to watch: agentic AI inside service platforms, usage-based pricing replacing per-seat licences, and ITSM, RPA, and workflow vendors merging into single suites.
Sources
- Mordor Intelligence — Service Delivery Automation Market
- Dataintelo — Service Delivery Automation Market
- Alloy Software — Automation in ITSM
- TechTarget — IT Service Delivery
Frequently asked questions
What is the service delivery automation market?
The service delivery automation market is the market for software and services that automate how organisations deliver services, from IT support and onboarding to claims and billing. It includes workflow platforms, RPA, AI triage, and the consulting and managed services that implement them.
How big is the service delivery automation market?
Estimates differ because definitions differ. Mordor Intelligence sizes it at USD 39 billion in 2025, rising to USD 159.27 billion by 2031, while Dataintelo puts it at USD 11.4 billion in 2025, rising to USD 32.83 billion by 2034. Both point to strong growth, but the range shows why the definition behind any figure matters.
What is the difference between service delivery automation and RPA?
RPA is a technique in which software robots mimic human clicks in existing applications. Service delivery automation is the broader outcome: an end-to-end service that may combine RPA with workflow engines, AI, and integrations so a request travels across teams without manual re-keying.
Which industries use service delivery automation most?
Banking and financial services is the largest buyer in Mordor Intelligence’s analysis, at 22.20% of the market in 2025, followed by IT and telecommunications, healthcare, retail, and manufacturing. Healthcare is forecast to grow fastest as providers automate scheduling, claims, and patient services.
How should a small business start with service delivery automation?
Start with one high-volume, low-risk service such as password resets or access requests, using your existing service-desk workflow tool. Measure first-response time, resolution time, and agent hours before and after, then expand only to services with a named owner and a clear process.