
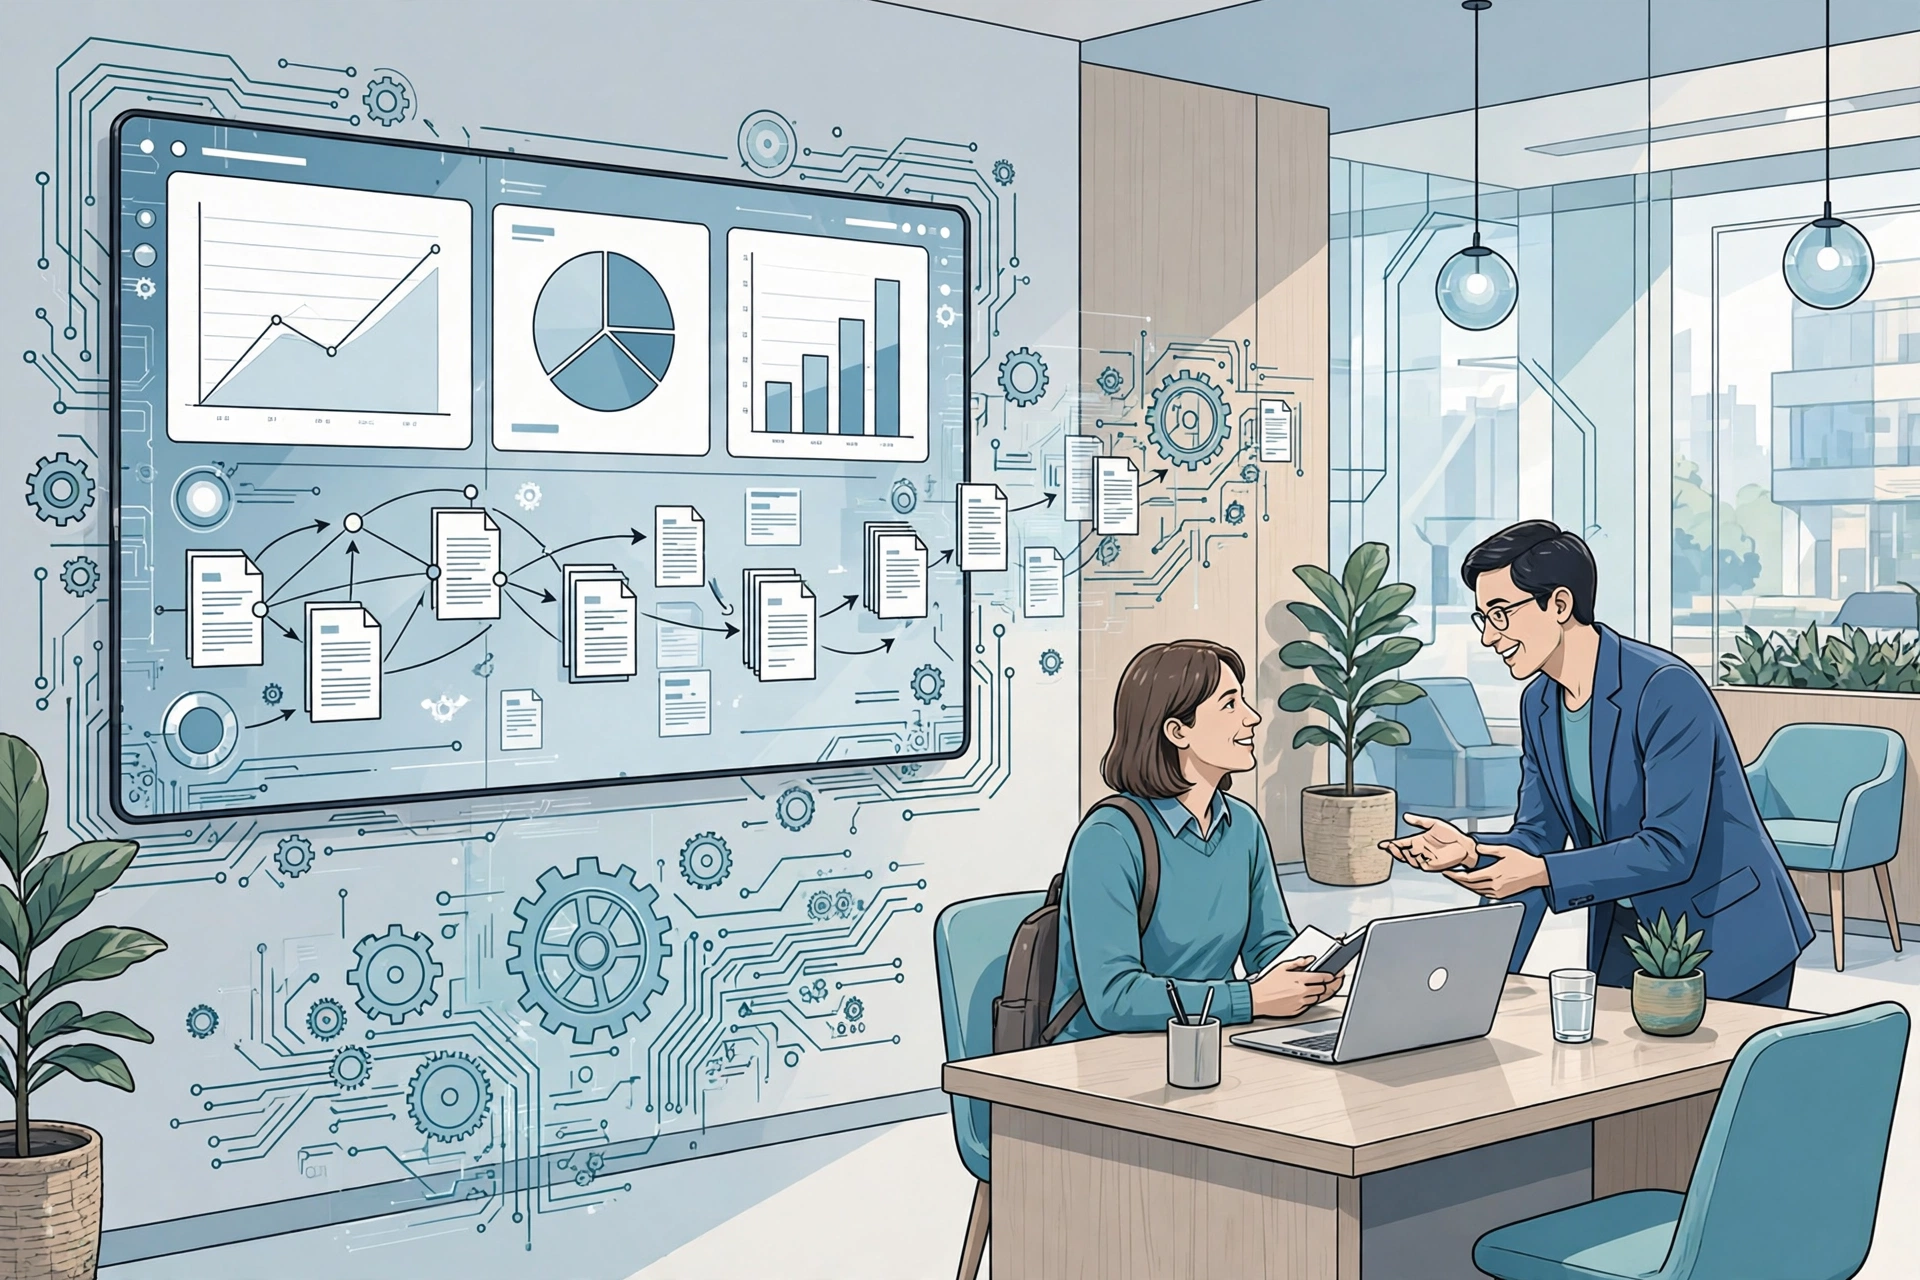
Intelligent Automation in Banking Explained: What It Is, How Banks Use It, and What It Changes
Key takeaway: Intelligent automation in banking combines robotic process automation (RPA) with AI, machine learning, and natural language processing to run banking workflows — from loan applications and fraud checks to customer onboarding and regulatory reporting. Unlike basic RPA, it reads unstructured documents, makes judgement calls within limits a human sets, and learns from exceptions instead of stopping at them.
What Is Intelligent Automation in Banking?
Intelligent automation in banking is the combination of robotic process automation (RPA) with artificial intelligence — machine learning, natural language processing (NLP), and computer vision — to automate banking workflows that involve variation, judgement, and unstructured documents. RPA on its own follows fixed rules: copy data from one system to another, fill in a form, send a standard reply. It stops when the input does not match the rule. Intelligent automation adds a cognitive layer that reads the document, classifies it, and decides what happens next within limits a human sets. Deloitte describes it as automation able to handle nonroutine tasks involving intuition, judgement, and problem-solving, rather than only repeatable ones.
The scale is large. McKinsey estimates generative AI could add $200 billion to $340 billion in annual value to banking — 9% to 15% of operating profits — if the use cases were fully implemented. An EY-Parthenon survey found 47% of retail and commercial banks had fully rolled out generative AI applications in 2025, up from 10% in 2023. Yet Capgemini’s World Cloud Report 2026 found 87% of financial firms use traditional automation, while only 10% have scaled fully autonomous AI agents.
Intelligent Automation vs RPA in Banking
The two are often confused, and vendors do not help. The practical difference is what happens when the input is messy — a scanned payslip, a free-text customer email, a transaction that almost matches a fraud pattern. RPA stops. Intelligent automation copes.
| RPA | Intelligent automation | |
|---|---|---|
| What it does | Follows fixed rules on structured data | Reads unstructured documents, classifies them, and decides within set limits |
| Exceptions | Stops and waits for a person | Routes exceptions and learns from them |
| Technology | Software robots | RPA plus AI, machine learning, NLP, and document intelligence |
| Banking example | Copying customer data between systems | Assessing a loan file, flagging a fraud pattern, screening a payment for sanctions |
| Cost and effort | Cheaper and faster to deploy | More expensive; needs training data, integration, and governance |
Where Banks Actually Use Intelligent Automation
The real deployments cluster in six areas. First, customer onboarding and KYC: reading identity documents, extracting the fields, and running sanctions and adverse-media screening. Second, lending: pulling data from payslips, tax returns, and bank statements to prepare credit files. Citi says its markets document processing frees more than 1,700 hours a month, according to BankingNewsAI’s 2026 deployment tracker. Third, fraud and anti-money-laundering: machine learning flags unusual patterns, and automation triages alerts so investigators see the riskiest cases first.
Fourth, compliance: Deloitte notes global banks use it to monitor employee communications for signs of noncompliant activity and to assemble regulatory reports. Fifth, customer service: Wells Fargo’s Fargo assistant has passed one billion interactions, and JPMorgan’s LLM Suite has 150,000 weekly users across 175-plus AI use cases in production. Sixth, engineering: JPMorgan reported 14,000 engineers using the agentic coding tool Devin, and Barclays routes about 120,000 markets emails a day through Claude. In trade finance, NatWest partnered with Cleareye.ai in the second quarter of 2026 to rebuild its back office on a platform called ClearTrade.
What Does Intelligent Automation in Banking Cost?
There is no standard price tag, and banks do not publish one. The bill has five parts: software licences (usually per bot or per user), implementation and integration with core banking systems — often the biggest line, because core systems are decades old — model validation and risk review, training, and ongoing maintenance. Budget 20–30% of the build cost per year to keep an automation running, as bots break whenever a target system changes.
The return is usually measured in hours saved and errors avoided rather than a single number. A 2019 Deloitte survey cited by Datamatics found executives expected intelligent automation to cut costs by an average of 22% and raise revenue by 11% over three years — expectations, not measured results. The simple check: multiply the hours saved per year by the loaded hourly cost of the people doing the work, and compare it with the full first-year cost. If payback is longer than 18 months, pick a smaller process first. For the wider project picture, see our guide to automation project management.
What Banks Need in Place First
Intelligent automation fails when it is bolted onto a mess. Four prerequisites decide whether it works. Documented processes: automating a broken process just produces errors faster, so the workflow has to be mapped as it actually runs. Clean, accessible data: models trained on inconsistent records make inconsistent decisions. Integration with core systems: the automation has to read from and write to the systems of record, not sit beside them. Governance with a named human owner: every automated decision needs an audit trail and a person accountable for it. No bank on record lets an AI agent make a credit decision or move a customer’s money without that customer’s instruction.
The Risks and Limits of Intelligent Automation in Banking
The risks are why adoption is slower than the marketing suggests. Models can misread documents, produce confident wrong answers, and inherit bias from training data — dangerous in lending and fraud decisions, where a wrong call has legal consequences. Regulators have not written a separate rulebook for AI agents: the April 2026 US model-risk guidance leaves them to broader governance, so banks must fit new tools into existing risk frameworks.
The sharpest warning came in October 2026. Between October 13 and 20, JPMorgan Chase, Charles Schwab, Citigroup, and Wells Fargo each moved to block or limit third-party AI agents that log in to customer accounts using the customer’s own credentials, according to law firm Hunton’s tracker. JPMorgan CEO Jamie Dimon cited “rogue agents” on the bank’s October 13 earnings call, and Chase’s updated Digital Services Agreement, effective January 1, 2027, treats anything an agent does with a customer’s access as authorised by the customer. The banks are not banning AI — each is building its own agent tools — but they draw a hard line at outside agents acting inside customer accounts. JPMorgan’s CFO added on the same call that the benefits of its AI deployments were not yet observable in quarterly earnings, with token costs offsetting some gains.
How This Affects You
If you bank with a large bank, intelligent automation is already shaping your experience: faster account opening, quicker loan decisions, fraud alerts that arrive before the damage spreads, and chat assistants that resolve routine issues without a hold queue. The trade-off: your bank may block a third-party AI agent from logging into your account, so use the bank’s own app and official open-banking connections (such as read-only data sharing through Plaid) rather than handing your login to an outside agent.
If you work in banking operations, the job is shifting from data entry to exception handling and oversight: reviewing what the automation flagged, fixing what it misread, and owning the outcome. Our explainers on digital automation solutions in banking and retail banking automation cover the neighbouring pieces, and AI agents for business automation explains the agent layer now being added on top.
Analysis: Governance, Not the Models, Is the Bottleneck
Analysis: The technology works — the evidence is 175 production use cases at one bank and a billion-assistant milestone at another. What is slow is everything around it: proving to regulators and auditors that a model behaves, keeping a human accountable for every automated decision, and wiring new tools into core systems built before the internet. Only 10% of financial firms have scaled fully autonomous agents, and that number is the honest measure of the field. The banks pulling ahead treat intelligent automation as a controlled workflow with named owners and audit trails, not as a chatbot demo. Expect the next year to be about governance and agent controls, not bigger models.
If you found this useful, add USABite as a preferred source in Google Search so our explainers surface when you look for them.
Frequently Asked Questions
What is intelligent automation in banking?
Intelligent automation in banking combines robotic process automation with AI, machine learning, natural language processing, and computer vision to automate banking workflows that involve variation and judgement. It reads unstructured documents such as payslips and ID cards, classifies them, and makes decisions within limits a human sets, rather than only following fixed rules on structured data.
How is intelligent automation different from RPA in banking?
RPA follows fixed rules on structured data and stops when the input does not match. Intelligent automation adds AI and machine learning so the workflow can interpret varied inputs, handle exceptions, and make context-aware decisions within defined limits. In practice, RPA copies data between systems, while intelligent automation assesses a loan file or flags a fraud pattern.
What are the best intelligent automation use cases in banking?
The strongest use cases are customer onboarding and KYC, loan origination and underwriting preparation, fraud detection and anti-money-laundering alert triage, payment processing and reconciliation, and document-heavy compliance work. The best candidates are high-volume processes with measurable outcomes and reasonably predictable exceptions.
How much does intelligent automation cost a bank?
There is no standard price. Costs cover software licences, implementation, integration with core banking systems, model validation and risk review, training, and ongoing maintenance — budget roughly 20 to 30 percent of build cost per year to run it. Banks usually judge payback on hours saved and errors avoided, and a 2019 Deloitte survey found executives expected average cost cuts of 22 percent over three years.
Is intelligent automation in banking safe?
It is safe when a human stays accountable: no bank on record lets an AI agent make a credit decision or move customer money without the customer’s instruction. The main risks are model errors in lending and fraud decisions, data privacy, and third-party agents misusing customer logins — which is why JPMorgan, Schwab, Citi, and Wells Fargo moved in October 2026 to block or limit outside agents logging in with customer credentials.
Sources: Deloitte, A Guide to Robotic Process Automation; Abrigo, AI and Generative AI Use Cases in Banking (McKinsey $200–340B estimate; EY-Parthenon survey); Eleks, What Is Intelligent Automation in Financial Services?; BankingNewsAI, AI Agents in Banking (2026); BankingNewsAI, AI in Investment Banking (2026); FinanceChief, NatWest, J.P.Morgan and Wells Fargo: Is it the AI or IA Era?; Hunton, Major Banks Move to Block or Limit Customer-Directed AI Agents; AI Press Review, AI in Banking: Deployments, Costs and Measured Results (October 2026).
One Comment
Comments are closed.